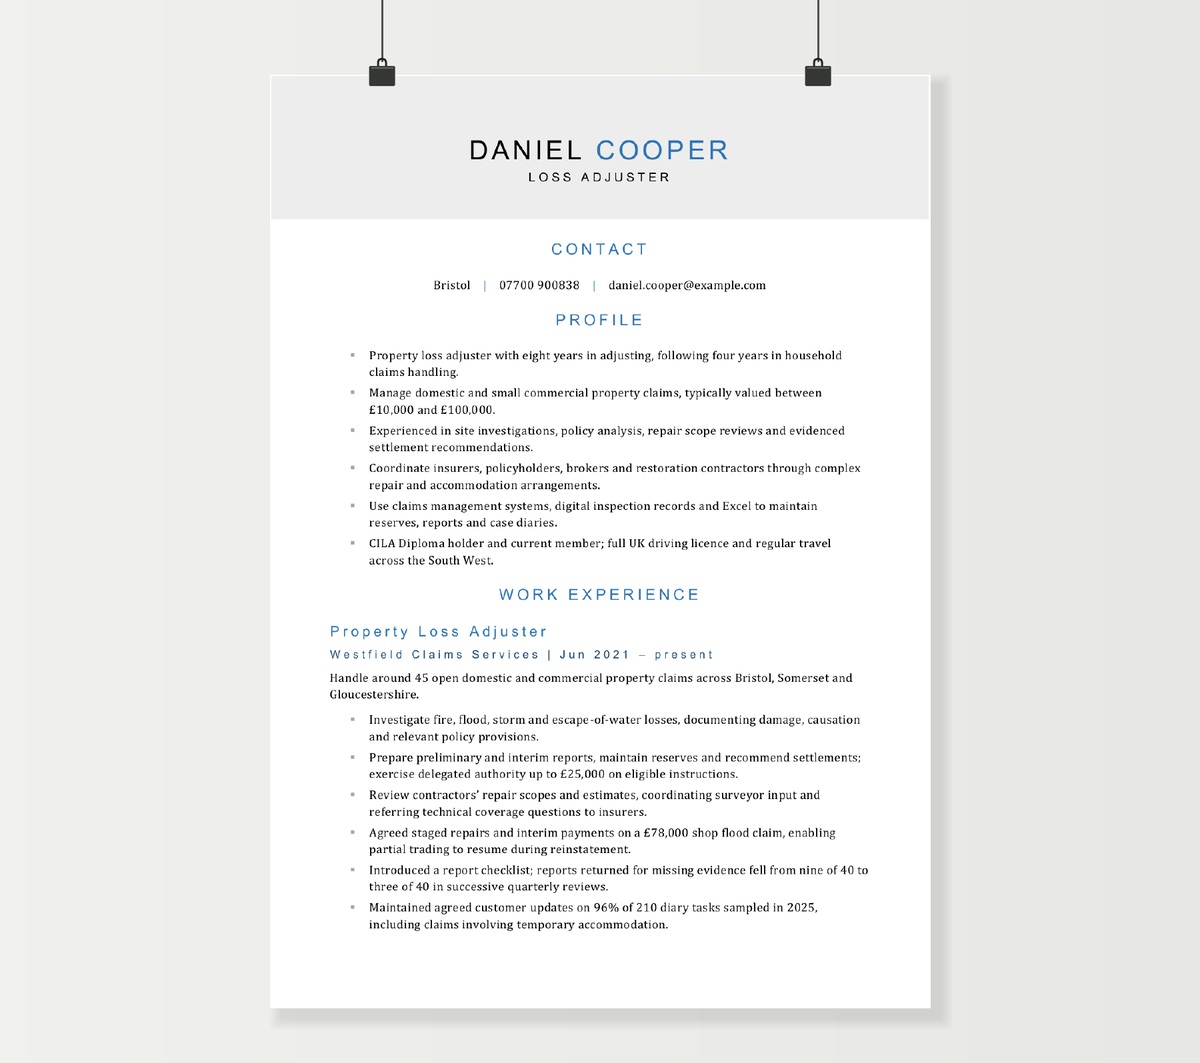
This loss adjuster CV template follows a property claims handler into trainee and field adjusting roles. The Word example presents domestic and small commercial losses, technical reporting and customer communication alongside measurable improvements. The guide also covers desktop, liability and major loss applications, with advice on demonstrating the judgement behind a well-managed claim.
Filename: FreeCVDownload_Loss_Adjuster.docx
Content of this CV template
Daniel Cooper
Loss Adjuster
Contact
Bristol | 07700 900838 | [email protected]
Profile
- Property loss adjuster with eight years in adjusting, following four years in household claims handling.
- Manage domestic and small commercial property claims, typically valued between £10,000 and £100,000.
- Experienced in site investigations, policy analysis, repair scope reviews and evidenced settlement recommendations.
- Coordinate insurers, policyholders, brokers and restoration contractors through complex repair and accommodation arrangements.
- Use claims management systems, digital inspection records and Excel to maintain reserves, reports and case diaries.
- CILA Diploma holder and current member; full UK driving licence and regular travel across the South West.
Work experience
Property Loss Adjuster
Westfield Claims Services | Jun 2021 – present
Handle around 45 open domestic and commercial property claims across Bristol, Somerset and Gloucestershire.
- Investigate fire, flood, storm and escape-of-water losses, documenting damage, causation and relevant policy provisions.
- Prepare preliminary and interim reports, maintain reserves and recommend settlements; exercise delegated authority up to £25,000 on eligible instructions.
- Review contractors’ repair scopes and estimates, coordinating surveyor input and referring technical coverage questions to insurers.
- Agreed staged repairs and interim payments on a £78,000 shop flood claim, enabling partial trading to resume during reinstatement.
- Introduced a report checklist; reports returned for missing evidence fell from nine of 40 to three of 40 in successive quarterly reviews.
- Maintained agreed customer updates on 96% of 210 diary tasks sampled in 2025, including claims involving temporary accommodation.
Trainee Loss Adjuster
Westfield Claims Services | Apr 2018 – May 2021
Progressed from supervised desktop investigations to accompanied visits and an allocated household caseload.
- Gathered photographs, statements and repair estimates, identifying outstanding evidence before adjuster review.
- Drafted reports and reserve updates for approval, developing experience in buildings and contents losses.
- Coordinated drying contractors and repair appointments, keeping policyholders informed of next steps.
- Helped clear 26 overdue contractor updates during a storm surge by agreeing dated actions with suppliers.
Household Claims Handler
Avonbridge Insurance Services | Sep 2014 – Mar 2018
Handled first notifications and progressed allocated household claims within team authority.
- Checked policy details, recorded loss circumstances and arranged emergency assistance.
- Reconciled supplier invoices and referred coverage queries with supporting file evidence.
Qualifications
CILA Diploma | 2021
Dip-CILA; CILA Certificate completed in 2018.
Education & development
Three A levels | Redland Sixth Form, 2014. Recent CPD: property reinstatement, vulnerable customer support and technical report writing, 2025–2026.
Interests
Coastal walking, cycling and playing guitar.
How to write a loss adjuster CV
A loss adjuster CV needs to establish what you can be trusted to investigate, assess and bring to a well-supported conclusion. The reader should quickly understand your claim specialisms, the complexity of your work and where your own decision-making begins and ends. A list of perils and qualifications is useful context; the strongest evidence comes from the claims you have progressed and the reasoning, reporting and coordination they required.
Define your claims experience before describing your strengths
Start with your main area: domestic property, commercial property, liability, third-party property damage, business interruption, subsidence, agriculture or another specialism. Add your level of experience and whether you work in the field, at a desk or across both. Someone recruiting for commercial fire losses should be able to distinguish that experience from a household escape-of-water portfolio immediately.
A useful profile might describe a property adjuster handling domestic and SME losses across a region, supported by experience in site investigations, repair scoping and insurer reporting. A senior liability applicant would put contested liability, construction exposures, expert evidence and complex negotiation much nearer the top. Choose the evidence that answers the particular vacancy.
Separate three numbers that are often blurred together: the typical value of an individual claim, your open caseload and your delegated settlement authority. For example, “40–50 open property claims, typically £10,000–£100,000, with settlement authority up to £25,000 on eligible instructions” gives a much clearer picture than “managed a £5 million portfolio”. If authority varies by client or scheme, a short qualification keeps the statement useful.
Show how you progress a claim, not just that you handle it
Under each role, give a short scope statement followed by selected examples of your contribution. Cover the parts of the claim lifecycle that you personally own: initial contact, investigation, policy consideration, reserving, mitigation, reporting, negotiation, settlement recommendations or closure. Earlier support work can show a narrower part of that process and still provide strong evidence of progression.
- Investigation: the evidence you gathered or evaluated, such as site observations, statements, photographs, maintenance records or specialist findings.
- Assessment: how you connected the evidence with causation, policy provisions, the extent of damage or the amount claimed.
- Action: the recommendation, instruction or agreement that moved the claim forward.
- Outcome: the practical result, whether that was an agreed repair scope, a supported reserve change, an interim payment or resolution of a disputed element.
For example, “Reconciled conflicting contractor scopes on a commercial escape-of-water claim and agreed a phased reinstatement plan with the surveyor and insurer” reveals more than “excellent problem-solving skills”. Add the resulting time, cost or operational benefit when there is a clear measure.
Make technical reports and reserves visible
Report writing is a central part of adjusting. Specify whether you prepare preliminary, interim and final reports, technical coverage referrals, quantum assessments or recovery recommendations. Then show what makes your reporting effective: a complete evidence trail, a clear explanation of outstanding issues, timely reserve revisions or recommendations that help the insurer make a decision.
Reserve experience also deserves more than a mention in a skills list. Describe the type of portfolio, your review responsibility and how you respond to new information. An example involving revised repair costs, accommodation duration or a specialist finding can demonstrate judgement. Where you contribute to a reserve reviewed by a senior colleague, describe that contribution directly.
File audits provide useful achievement evidence. Give the review period, sample size and measure: reports accepted at first technical review, missing evidence reduced, or reserve reviews completed within an agreed interval. These are more informative than an unexplained “98% accuracy” claim.
Choose examples that suit the claim specialism
For property claims, employers need to see how your building knowledge supports the assessment and reinstatement process. Include relevant perils, premises types, schedules of works, contractor estimates, restoration arrangements and the surveyor or engineer input you coordinate. A good CV explains your role in agreeing an appropriate scope or resolving a repair dependency rather than listing construction terminology.
For liability and third-party property damage, concentrate on the circumstances of the incident, relevant parties, evidence evaluation, quantum, negotiation and the experts involved. Construction claims may add contractual relationships and technical investigations. Show the contribution you made to the insurer’s position and the resolution of disputed issues.
For business interruption, identify the businesses and loss situations you have worked with, your responsibility for the financial assessment and how you coordinated with property adjusters or accountants. Distinguish assessing an interruption claim from collecting turnover figures or referring the work to a specialist. Both can be relevant, but they demonstrate different levels of experience.
For major and complex losses, value alone rarely explains the challenge. A short case example can identify multiple stakeholders, a difficult cause investigation, prolonged reinstatement, linked policy issues or a business that needed to keep operating. Explain the decisions and dependencies you managed, then the outcome.
Connect customer communication with claim progress
“Customer focused” becomes persuasive when the CV shows how you kept people informed during an uncertain situation. Useful examples include agreeing a contact plan, explaining the next stage of an investigation, coordinating temporary accommodation or arranging an interim payment while the full loss was assessed.
For a property claim involving a displaced household or an interrupted business, communication and technical work are closely connected. Show how you coordinated policyholders, brokers, insurers, contractors and experts so that decisions or repairs could proceed. When a customer required additional support, focus on the practical adjustment you arranged and the continuity of service.
Complaints experience can be valuable too. Explain whether you investigated the file, produced the chronology, clarified an earlier decision or coordinated remedial action. That provides evidence of judgement and clear writing without devoting a large section to a single difficult conversation.
Use measures that reflect a well-managed claim
Choose results that balance technical quality, customer outcomes and operational performance. Report turnaround, overdue actions, first-contact times, file audit results, reserve review compliance and contractor response times can all help. State the period and population so the reader understands the scale.
Settlement value and savings need context. A reduction between an initial estimate and an agreed scope may reflect duplicated items, revised evidence or a different repair solution. Describe that reason and your contribution. The amount paid is not, by itself, a measure of the quality of adjusting.
Operational examples can be equally strong: securing approval for staged repairs, resolving a supplier delay, improving handovers during a weather event or getting a substantiated interim payment agreed. Where several people contributed, use wording such as “coordinated”, “recommended” or “worked with” to make your role clear. The example CV uses a report-review sample and a customer-update measure alongside a reinstatement case, giving a rounded view of performance.
Present systems, field work and workload control together
Name the claims platforms, estimating tools, inspection applications or reporting systems you use where they matter to the vacancy. Connect each to a task: maintaining case diaries, recording site evidence, preparing repair estimates, reviewing reserves or monitoring service deadlines. Excel becomes more useful evidence when attached to a reserve reconciliation or workload report than when labelled “advanced” without explanation.
For field roles, include your location, geographical coverage and driving licence in an accessible place. Examples of planning visits alongside urgent customer contact and reporting deadlines show how you work independently. Desktop applicants can demonstrate the quality of remote investigations, the assessment of third-party reports and the point at which a site visit or specialist review was arranged.
If you have handled surge work after storms or floods, give the additional workload, the period and your role in keeping priority actions moving. A busy month is more convincing when connected to triage, diary control, contractor coordination or successful handovers.
Make qualifications and progression easy to assess
Give the full qualification name, awarding body and completion year. Use the appropriate current designation where relevant, such as Dip-CILA. An award, membership grade and chartered status convey different things, so present each clearly. For study in progress, name the award and the stage reached; completed units or a booked assessment may be more useful than a broad intention to qualify.
CILA and CII qualifications are relevant to many adjusting roles. Building, surveying, legal, accounting or restoration credentials may be particularly valuable for certain claim types. Include recent professional development selectively, linking it to your work: reinstatement, liability investigation, technical reporting or customer support, for example.
A trainee application should make existing claims experience prominent. Show the decisions already made within your role, reports drafted, evidence evaluated and contact with policyholders or suppliers. Applicants moving from surveying can draw on inspections, defect analysis, scopes and cost assessment; the building surveyor example offers another way to present that technical background.
At senior level, give more space to complex cases, technical referrals, mentoring, file review and client relationships. If you have helped retain an insurer account or developed a service, explain your part in the relationship and the result. Leadership should add to the picture of your adjusting expertise, with enough recent case evidence to show that expertise remains current.
Loss Adjuster CV FAQs
Use the same career record, but change the emphasis. For an insurer role, bring out end-to-end customer outcomes, authority, internal referrals and the insurer’s claims processes. For an independent practice, make experience of different insurer instructions, reporting requirements, service agreements and broker relationships easy to find. If you have worked in both settings, a short scope line under each employer helps the reader understand the difference.
State that the case is ongoing and focus on completed milestones: the investigation, agreed reserve, approved interim payment, appointed experts or reinstatement stage. Give the current value basis, such as an estimated loss or reserve, rather than presenting it as a final settlement. An open case can demonstrate substantial responsibility before it reaches closure.
The CV can usually demonstrate report-writing ability through the reports you prepare and their purpose. If an employer requests a sample, an authorised, anonymised extract or a separately prepared technical exercise can show your structure and reasoning. Agree the format first; a lengthy claim file is rarely necessary for an initial application.
List the substantive employer and role, then identify the assignment, event type, region, duration and duties beneath it. Several short deployments can sit together in a compact assignments section. Distinguish your own case allocation from the wider team’s volume and explain whether you conducted visits, produced reports, managed contractors or supported another adjuster.
It depends on the level and specialism. Trainee, desktop and property roles may accept relevant claims experience with certificate or diploma qualifications, while some senior and specialist vacancies seek chartered status or progress towards it. Put your achieved qualification and current professional status where they can be assessed quickly, followed by relevant study in progress.
Keep the employer’s title and add a short description of your remit, such as household technical claims or desktop property investigations. Evidence of policy analysis, repair scope assessment, reserve decisions and settlement recommendations helps the recruiter evaluate the work itself. A profile can then explain the move into the loss adjusting role you are seeking.