This mortgage adviser CV template follows a CeMAP-qualified adviser who progressed from customer service and mortgage administration into advice. The Word example combines client conversations, lender research and case management with clearly defined results. The guide covers experienced advisers, newly qualified applicants and candidates moving between lender, brokerage and self-employed roles.
Filename: FreeCVDownload_Mortgage_Adviser.docx
Content of this CV template
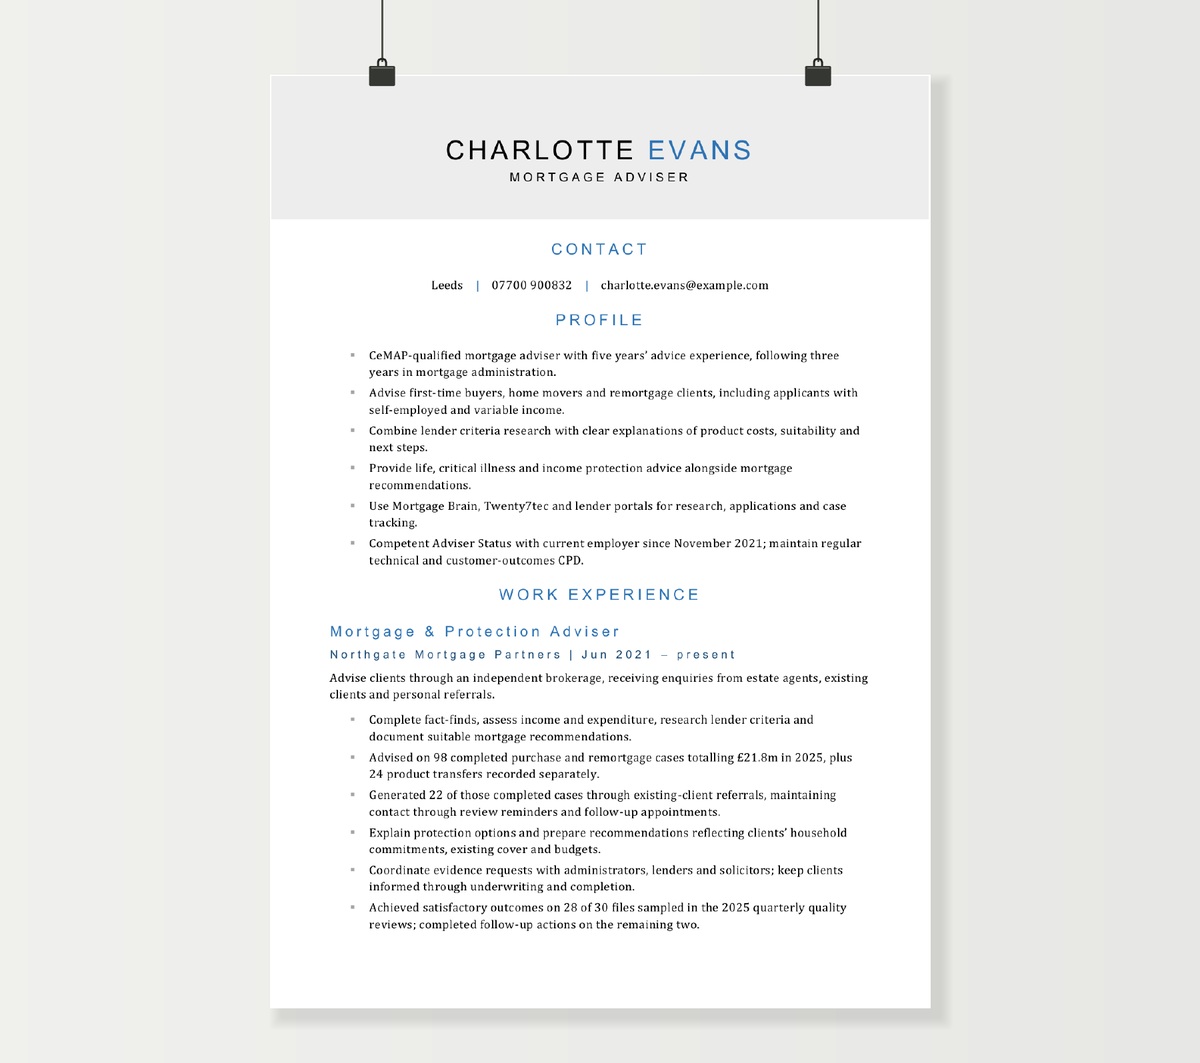
Charlotte Evans
Mortgage Adviser
Contact
Leeds | 07700 900832 | [email protected]
Profile
- CeMAP-qualified mortgage adviser with five years’ advice experience, following three years in mortgage administration.
- Advise first-time buyers, home movers and remortgage clients, including applicants with self-employed and variable income.
- Combine lender criteria research with clear explanations of product costs, suitability and next steps.
- Provide life, critical illness and income protection advice alongside mortgage recommendations.
- Use Mortgage Brain, Twenty7tec and lender portals for research, applications and case tracking.
- Competent Adviser Status with current employer since November 2021; maintain regular technical and customer-outcomes CPD.
Work experience
Mortgage & Protection Adviser
Northgate Mortgage Partners | Jun 2021 – present
Advise clients through an independent brokerage, receiving enquiries from estate agents, existing clients and personal referrals.
- Complete fact-finds, assess income and expenditure, research lender criteria and document suitable mortgage recommendations.
- Advised on 98 completed purchase and remortgage cases totalling £21.8m in 2025, plus 24 product transfers recorded separately.
- Generated 22 of those completed cases through existing-client referrals, maintaining contact through review reminders and follow-up appointments.
- Explain protection options and prepare recommendations reflecting clients’ household commitments, existing cover and budgets.
- Coordinate evidence requests with administrators, lenders and solicitors; keep clients informed through underwriting and completion.
- Achieved satisfactory outcomes on 28 of 30 files sampled in the 2025 quarterly quality reviews; completed follow-up actions on the remaining two.
Mortgage Administrator
Northgate Mortgage Partners | Apr 2018 – May 2021
Supported three advisers with residential purchase and remortgage applications while completing CeMAP in 2020.
- Checked application packs for identity, income and deposit evidence before adviser review and lender submission.
- Tracked valuations, offers and outstanding conditions, liaising with lenders, estate agents and conveyancers.
- Introduced a case-document checklist that reduced incomplete packs returned for missing evidence from 12 to five per month over one quarter.
- Maintained client records and renewal dates, arranging review appointments ahead of fixed-rate expiry.
Customer Service Adviser
Westfield Retail Services | Sep 2015 – Mar 2018
Handled telephone and email enquiries about orders, payments and account updates.
- Resolved billing queries and explained options clearly, recording agreed actions and follow-up dates.
- Supported new colleagues with call handling and accurate customer records.
Qualifications
Certificate in Mortgage Advice & Practice (CeMAP)
The London Institute of Banking & Finance | 2020
Education & development
A levels: Business Studies, English and Psychology | Leeds sixth-form college, 2015. Recent CPD: self-employed income, protection underwriting and vulnerable customer support, 2025–2026.
Interests
Swimming, reading crime fiction and weekend walks in the Yorkshire Dales.
How to write a mortgage adviser CV
A mortgage adviser CV needs to show two things together: that you can guide clients through a suitable recommendation, and that you can manage a productive caseload. Qualifications and adviser status help establish your starting point. The stronger evidence comes from the types of clients you advise, the research and communication you undertake, and the quality of the business you complete.
Put your qualification and advice status near the top
Make your completed mortgage qualification easy to find in the profile and qualifications section. Give its full name, awarding body and completion year. CeMAP and the CII Certificate in Mortgage Advice are recognisable routes; the precise award is more useful than a broad statement that you are qualified in financial services.
If you have Competent Adviser Status, give the firm or network context and the date it was achieved or most recently held. “CAS with current employer since November 2021” helps a recruiter understand your recent advice experience. Keep the qualification and competence assessment as separate facts: completing an examination and being assessed by a firm for an advice role demonstrate different things.
Newly qualified applicants can state the completed qualification and then show relevant client-facing or mortgage-support experience. For study in progress, name the award and the units or modules completed under your programme, together with a scheduled assessment where useful. This gives employers a clear picture of your stage of development.
Explain the clients and mortgage work you handle
Under each role, describe the advice environment. Include the main client types, products and source of opportunities. First-time buyers, home movers, remortgage clients, landlords and borrowers with complex income each call for different evidence. Select the mix that reflects your work and is relevant to the next role.
Make the market-access model understandable. Experience advising on one lender’s range, a selected panel or a broader market offering gives employers different context. A lender-based adviser can still demonstrate strong fact-finding, suitability, communication and case-management skills when moving to a brokerage. The experience section can make those transferable strengths explicit.
Describe the support around you as well. In one role you may conduct the initial fact-find and manage the case through completion; in another, pre-application and administration teams handle much of that work. A short scope line helps the reader interpret both your responsibilities and your case volumes.
Choose cases that demonstrate advice judgement
“Sourced suitable mortgages” is a useful summary, but a stronger CV gives an example of what made the work demanding. Consider a client with variable earnings, a self-employed applicant, an unusual property or a purchase with a tight timeline. Explain the relevant challenge, your research and the part you played in progressing the case.
For example, you might describe reviewing a self-employed client’s income evidence, clarifying criteria with lenders and explaining the available options before an application was submitted. This shows how you connect research with a recommendation. It is more informative than listing every borrower category you have encountered.
Keep the example short and focused on your work. A CV needs enough detail to reveal judgement; the full affordability assessment and recommendation belong in the case record. An anonymised description of the applicant’s circumstances and your contribution will usually provide sufficient context.
For specialist vacancies, bring the most relevant work forward. Buy-to-let, complex credit, contractor income, second-charge lending or later-life advice may each deserve a separate skills line and selected case evidence. Relevant qualifications and the scope of your advice should sit alongside that experience.
Use performance figures that a recruiter can interpret
Choose measures that explain the volume, complexity and commercial contribution of your work. A full year or another clearly stated period gives the reader a fairer basis for comparison than an isolated best month.
- Completed cases: give the number and main case types. State separately whether product transfers are included.
- Lending volume: identify it as completed mortgage lending, and pair it with case count where that adds context.
- Business income: define whether the amount is submitted, written or received income, and what mortgage or protection business it covers.
- Conversion: name both stages, such as attended appointments to applications, with the period and lead source.
- Quality: include the sample and assessment basis when using file-review outcomes, alongside any service or process improvement.
The example CV separates 98 completed purchase and remortgage cases from 24 product transfers. Its £21.8m figure describes lending volume, rather than adviser earnings or brokerage income. This makes the result easy to understand without requiring a recruiter to reconstruct the reporting basis.
Conversion figures benefit from the same care. Pre-qualified appointments, new online enquiries and existing-client reviews start at different points in the customer journey. A brief explanation of the opportunities you receive makes your result more useful. If a case-management team supports completion, describe the collaboration alongside your own advice responsibility.
Give protection work the right amount of space
Mortgage and protection roles vary considerably. If you advise on protection, name the relevant products and show how you connect recommendations to household commitments, existing cover and the client’s priorities. Life cover, critical illness cover and income protection can be grouped in a concise skills line, with a work example where useful.
If you refer clients to a protection specialist, describe how you identify the need, arrange the handover and maintain continuity. This is valuable client-service work in its own right. It also helps an employer understand the training or support that would accompany a move into a combined role.
For a protection result, explain the basis of the measure. Policy count, clients advised and income received describe different outcomes. Pair commercial evidence with the quality of the conversation and follow-through, so the CV shows the advice behind the business.
Demonstrate the client relationship beyond the appointment
Employers value advisers who keep a case moving and maintain trust when there are delays or difficult decisions. Useful evidence includes explaining underwriting requests, coordinating with solicitors, managing an expiring offer or helping a first-time buyer understand the sequence of next steps. Describe the communication and coordination you own.
Introducer relationships can be important, particularly in estate-agency and new-build settings. Say how you work with those contacts: keeping appointments available, providing appropriate progress updates, attending branch meetings or resolving handover issues. A number of active relationships or resulting cases may help establish scale.
Existing-client reviews and referrals can demonstrate the longer-term relationship. The example identifies 22 completed cases originating from client referrals. Review diaries, product-expiry contact and repeat business can offer equally useful evidence, depending on your role.
Show advice quality through practical work
A statement that you follow FCA requirements is less informative than evidence of how you produce a clear, well-supported recommendation. Your CV can refer to complete fact-finds, recorded research, suitability explanations, review feedback and timely completion of follow-up actions. Select the elements you regularly handle.
Customer outcomes also have a place in the experience section. Examples might include adapting the pace or format of an appointment, explaining a change in the available options, or improving the way clients receive document requests. Describe what you did and why it helped the customer understand or progress the case.
For a senior adviser or team leader, add coaching, observed appointments, file-review work or support for trainees moving towards competence. Explain the extent of the responsibility. Mentoring a colleague, reviewing a submission and formally assessing competence are distinct contributions.
Describe sourcing and case systems through their use
Name the sourcing, criteria and CRM platforms relevant to your work, followed by what you do in them. Mortgage Brain, Twenty7tec, lender portals and employer systems may support different parts of the process. A short description of research, recorded comparisons, applications and pipeline tracking is more useful than a long software list.
A process improvement can be a strong achievement, particularly for someone progressing from administration. A document checklist, clearer case handover or more reliable review diary demonstrates understanding of the mortgage journey. Explain the problem it addressed and any measurable reduction in rework or delay.
Adjust the emphasis for your next step
For a newly qualified adviser, bring mortgage administration, customer service, sales conversations and learning into the foreground. A support role can provide evidence of document handling, lender communication, case progression and client care. The administrator CV example can help you select useful earlier experience before giving mortgage work greater prominence.
An experienced adviser should lead with recent advice, case mix, outcomes and current competence. Someone moving into self-employment can add experience of referrals, introducer relationships, diary management and building repeat business. Where a role supplies enquiries, show how you manage and convert that flow as well as the quality of your recommendations.
For a return after a break, give the dates of your last advice role and relevant recent development. This lets an employer assess your experience and the support needed to return to its advice process. Earlier qualifications remain part of your record; current knowledge and practical readiness deserve their own evidence.
You can find alternative layouts in the Word template library. Choose one that makes qualifications, recent advice experience and clearly defined results easy to find.
Mortgage Adviser CV FAQs
Both spellings appear in UK vacancies. You can match the employer's spelling in your professional headline and application wording while keeping your actual employment titles. There is no need to repeat both versions throughout the document; relevant mortgage experience and clear qualifications matter far more.
A new firm will assess your competence under its own training and supervision arrangements. Your previous CAS history is useful evidence, so give the firm and dates, alongside recent advice experience. The receiving firm can then decide what assessment, induction and supervision are appropriate for its role.
Yes, where the vacancy offers a trainee or newly qualified route. Make the completed qualification clear and present the work that demonstrates readiness for supported advice: client conversations, mortgage administration, research or case progression. Some experienced vacancies require recent CAS, while others provide a route towards it.
State that the role was self-employed and give the brokerage or trading business through which you worked, with dates and the nature of the arrangement where useful. Explain your client sources, advice responsibilities, support structure and results. This makes the experience understandable alongside employed adviser roles.
Yes. Give the full name of the qualification you completed and the awarding body. The CII Certificate in Mortgage Advice meets the FCA's qualification requirements for mortgage advisers. Many vacancies ask for CeMAP or an equivalent qualification, so spelling out your award makes the relevant route clear.
Usually the applicant's circumstances, the challenge, your contribution and the stage reached are more useful. Rates date quickly and may depend on details that a short CV cannot explain. A lender name can help establish a particular working relationship, but it is rarely necessary to demonstrate the quality of your research or advice.